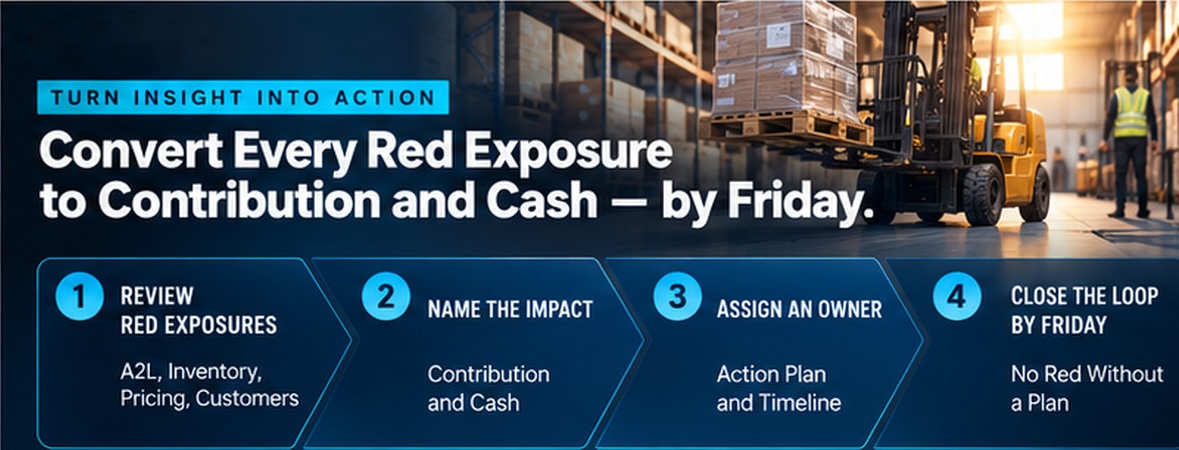
Hold the Line Through Tuesday’s Watsco Q3. Then Convert Every Red Exposure to Contribution and Cash — by Friday.
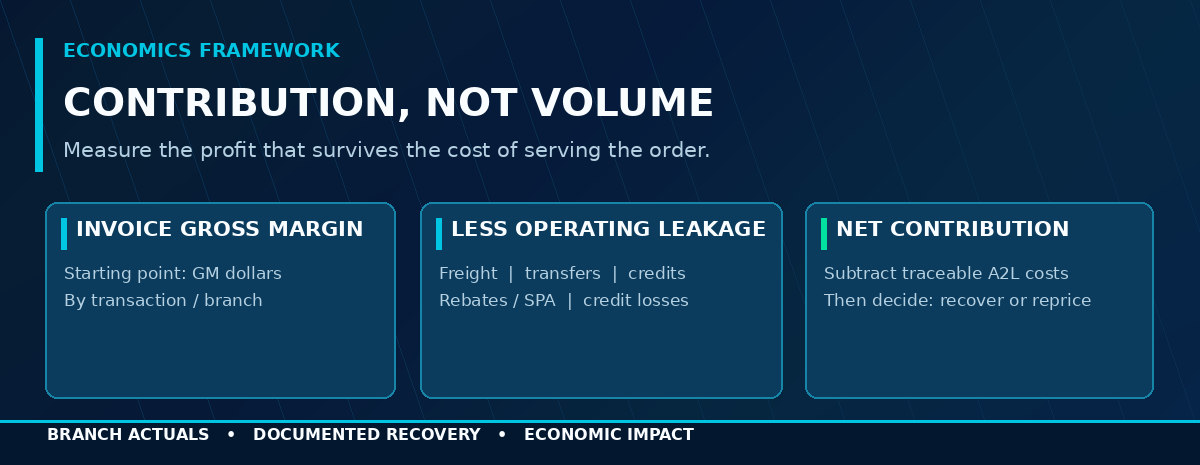
The goal is not to match Watsco’s commentary. The goal is to determine whether each branch is converting A2L pricing and volume into net contribution, cash, and defensible contractor wallet share after freight, transfers, credits, supplier-program leakage, inventory risk, and credit exposure.
This week · the operating question
Can every branch show, by Wednesday close, where its A2L margin, inventory conversion cost, and demand trajectory track or diverge from Watsco’s Tuesday Q3 commentary — with the explanation named, not implied?
Evidence hierarchy for this week’s decisions
1 Branch transaction data — decision-grade · 2 Supplier written confirmation — decision-grade for recovery and procurement · 3 Watsco Q3 commentary — directional external benchmark · 4 Trade reporting / public commentary — context only
Weekly Net Contribution definition in §04; six KPIs with materiality gates in §06; cadence in §05; Friday register in §13. Fixed branch occupancy and management overhead are reviewed separately and should not delay action on transactional leakage.
01
Weekly Change Log · what’s new since last Monday
NEW · WATSCO CLOSES GRANITE — NORTHEAST OVERLAP MAP DUE FRIDAY
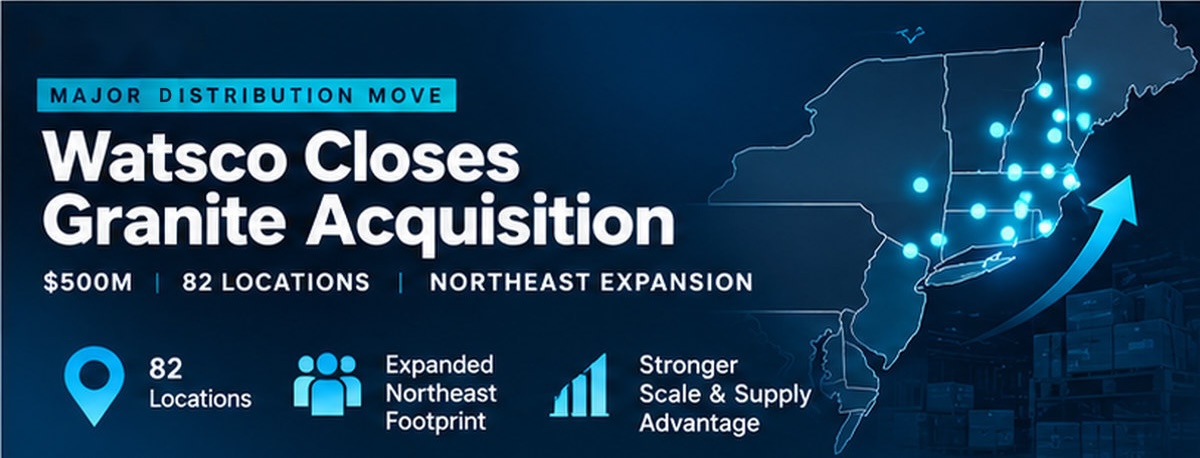
Watsco completed The Granite Group acquisition October 12: approximately $500M annual revenue, 82 locations across seven Northeast states (NH, VT, ME, MA, CT, RI, NY), Granite leadership retained. Follows the June 1 close of Jackson Supply ($230M, 25 Sunbelt locations). Do: Northeast distributors build overlap map by branch, vendor line, and shared contractor account by Friday close (§08, §11, §13).
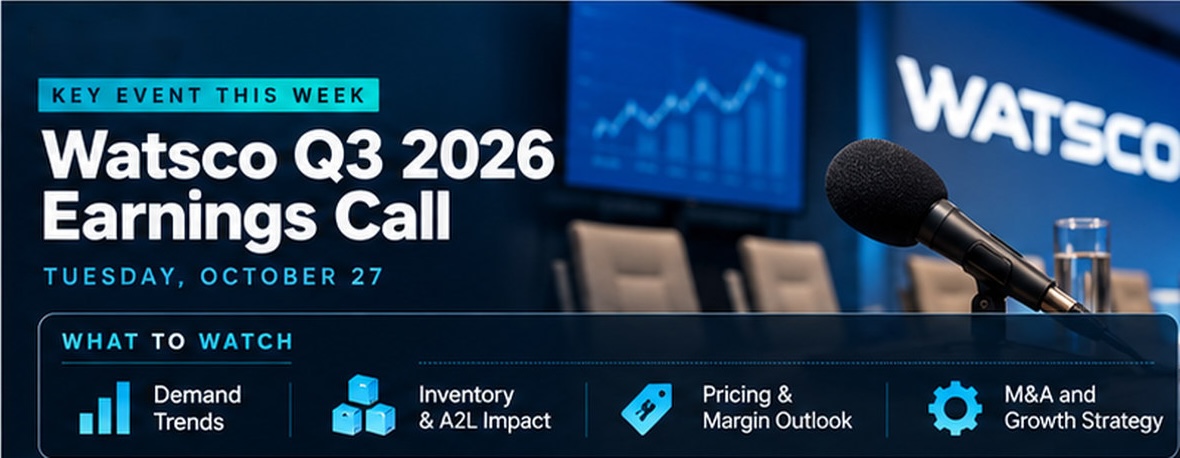
NEW · WATSCO Q3 2026 CALL SCHEDULED TUESDAY OCT 27, 10:00 A.M. EDT
Per Watsco’s investor-relations calendar; results released before market open. This week’s dominant external datapoint on A2L margin realization, inventory conversion cost, demand trajectory, and Q4 outlook. Do: Monday pre-stage, Tuesday listen, Wednesday compare — divergence must be named, not implied (§05).
NEW · CENSUS SEPTEMBER 2026 RESIDENTIAL CONSTRUCTION RELEASED OCT 20
National construction indicators remain mixed per the Oct 20 release. Do: use only as a prompt to test local release schedules, replacement demand, and contractor cash conditions; builder-heavy branches require release schedules, credit evidence, and project cash controls before any incremental project credit extension (§06 KPI 6).
CARRIED · HARDI AUG +7.6%; AHRI AUG 756,739 UNITS; NEXT RELEASES NOVEMBER
HARDI September TRENDS and AHRI September shipment data land in early-to-mid November. Treat July–August as unproven until September distributor and shipment data arrive; test branch-level September contribution now, not after.
02
Weekly Thesis · three operating risks
WEEKLY THESIS · CONFIDENCE: HIGH
Hold-the-line week with a midweek public catalyst. Last week’s posture holds. The job is to use Tuesday’s Watsco Q3 print as a reality test on branch-level A2L margin, conversion cost, and demand trajectory — not as permission to loosen quote, freight, credit, or buy-ahead discipline.
R1 · WATSCO Q3 MISREAD
Management reads Tuesday’s print (beat or miss) as a direct read-through on branches without testing own A2L margin, conversion cost, and demand profile against it. Action: Finance publishes branch-level A2L view by Monday close; regions bring documented compare to Wednesday review.
R2 · NORTHEAST CONSOLIDATOR OVERLAP
Watch for early evidence of post-close integration effects — supplier-program discussions, shared-account approaches, allocation changes, pricing actions, technology or digital-tool positioning, leadership or branch-network moves. Do not assume they are occurring without evidence. Action: Regional VP delivers overlap map (branch / vendor line / shared account) and account-defense criteria by Friday 4 p.m.
R3 · SEASONAL AR RAMP MASKING CREDIT STRESS
Normal seasonal DSO ramp into Q4 masks real credit deterioration in builder, PE-backed, and thinly capitalized owner-led replacement accounts. First clear read lands only when Q1 cash arrives weaker than planned. Action: CFO reviews AR aging by contractor segment, not just by account; concentrated bucket migration gets Stopped / Escalated / Account Exception License by Friday.
What would prove the hold-the-line posture wrong
·
A2L contribution stable or improving after conversion cost and leakage
·
R-410A disposition risk covered by documented returns, sell-through, or reserves
·
Contractor wallet share stable without below-floor account exceptions
·
Freight and transfer leakage falling, not shifting between branches
·
AR aging seasonal and broad-based rather than concentrated in vulnerable accounts
·
Watsco commentary confirms demand and pricing consistent with internal branch evidence
03
External Context · three new primary signals
M&A · WATSCO CLOSES THE GRANITE GROUP — OCT 12
~$500M revenue, 82 locations across NH, VT, ME, MA, CT, RI, NY. Granite operates as independent subsidiary under existing leadership. Watsco’s second announced 2026 acquisition of this scale after Jackson Supply ($230M, 25 Sunbelt locations, closed June 1). phcppros.com
Scheduled per Watsco investor relations; results before market open. Q3 2025 reference anchors: sales −4% to $2.07B, GM 27.5% (+130 bps), A2L ~55% of mix per management commentary, Q4 pressure acknowledged. phcppros.com
HOUSING · CENSUS SEPTEMBER 2026 RELEASED OCT 20
National construction indicators remain mixed per the Oct 20 release; use only as a prompt to test local release schedules, replacement demand, and contractor cash conditions. Local builder-account data is the operating input, not the headline. census.gov
CARRIED · HARDI AUG +7.6% / DSO <37 / HARDI SEP IN EARLY NOV
July + August called best back-to-back since late 2022; HARDI acknowledged warmer prior-year August comp help. September TRENDS typically releases in the first week of November. achrnews.com
AHRI public commentary continues to describe R-410A supply as currently ample, with reclaim capacity flagged as the long-term constraint. Industry reporting indicates elevated R-410A inventories at many distributors. A2L converted lines carry the heaviest near-term price-file churn and conversion cost. achrnews.com
04
Weekly Net Contribution · definition — with A2L scope
A2L conversion cost includes only incremental, traceable costs caused by the transition: documented training and technical-support burden above normal run rate; incremental delivery, handling, return, or warranty cost directly tied to conversion; documented rework or compatibility-issue cost; approved inventory conversion / disposition cost. It does not include normal branch labor, generalized overhead, or unsupported allocations.
05
M/T/W/F Operating Cadence
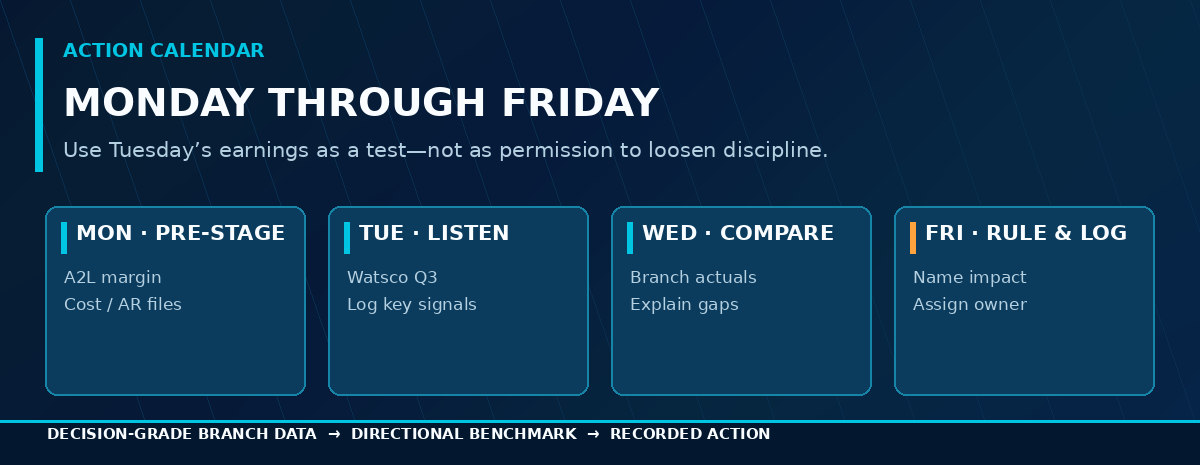
MON · PUBLISH & PRE-STAGE
Finance publishes branch-level A2L realized margin and conversion-cost view. Purchasing publishes affected vendor-line file (§08) with Northeast overlap flags. Credit publishes AR aging by contractor segment. Branches pull top 25 negative contribution variances; identify stale quotes; rank platform inventory (A2L and R-410A separately).
TUE · LISTEN & LOG
10:00 a.m. EDT: Watsco Q3 2026 earnings call. Log A2L margin realization language, inventory conversion cost disclosure, pricing posture into 2027, demand trajectory by segment, Q4 outlook, Northeast / Granite integration references. Deliverable: one-page summary with named implications for Wednesday.
WED · CONVERT & COMPARE
Regions bring branch-level A2L margin, conversion cost, and demand profile and compare explicitly against Watsco Tuesday commentary — divergence is named with a reason. Normalization caveat: use Watsco as a directional signal, not a target or proof point — normalize for branch mix, market, vendor programs, inventory position, contractor concentration, and acquisition effects before drawing an operating conclusion. Contact suppliers for documented protection. Reprice / recover freight, transfer, delivery leakage. Validate project release schedules before extending credit. Prepare red items for Friday.
FRI · RULE & LOG
Every red exposure receives one of eight rulings with expected contribution and cash impact stated (§13). Northeast competitive-overlap items get an account defense plan with a stated walk-away point (§11).
06
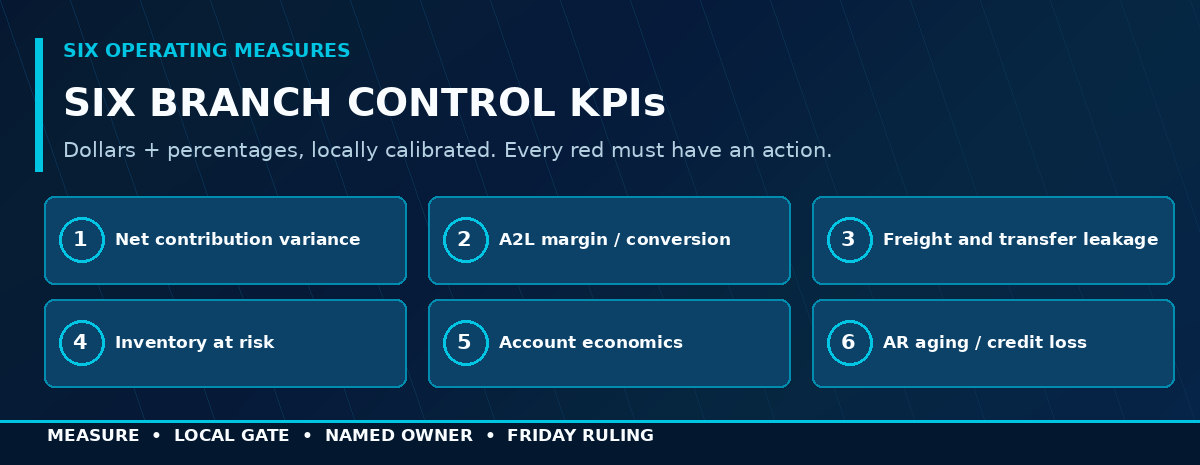
Six Operating KPIs · measures, gates, Friday actions
Each company sets its own dollar gate and percentage-of-contribution gate; red gates below are illustrative. Regional leaders may prioritize the largest dollar exposures first — the purpose is not to create a reporting exercise but to remove economically material leakage while branch teams continue serving contractors.
KPI
Required measure
Illustrative red gate
Friday requirement
1 · Weekly Net Contribution variance CFO + Regional VP
Required measure Current vs prior / 4-week avg; dollars and bps per §04
Illustrative red gate Below company contribution gate on a branch-calibrated dollar or % basis
Friday requirement Name top three drivers; choose ruling; quantify weekly and annualized impact
Supplier-recovery documentation discipline (written evidence + Finance probability weighting + escalation on material disputed claims) runs through every KPI with a supplier-dependent assumption; no management credit without written evidence.
Costs are not settling; copper continues to drift upward through October. Branch read: cost-file discipline is where margin is protected or lost. Do not price October quotes on September cost files, especially on cooling-side SKUs and copper-intensive service parts.
Component
Weight
This week
Operating read
Copper
Weight 30%
This week +0.9%
Operating read Elevated; hold margin on coils, motors, linesets, wire, service parts
Steel / galvanized
Weight 30%
This week Firm · dir.
Operating read S232 tariffs continue to keep domestic steel firm; no basis to give back price
Operating read Copper move raises motor input cost; directional
Controls
Weight 7%
This week ~Flat · dir.
Operating read Monitor as A2L system controls evolve
Index = weighted weekly move of six components, Jan 2025 = 100. Copper and aluminum from Markets Insider closes; steel, compressors, motors, controls are directional. The index is context, not a repricing trigger — use the action set below.
Branch action triggers · what actually moves price
·
Vendor price-file effective date reached or changed
A2L-equipped cooling continues to carry pricing; furnace side essentially flat. Age out and refresh cooling-side quotes older than 14 days before extending; validate furnace quotes against current vendor files but with a lighter touch.
Public comps & macro
Instrument
Level / move
What it means
Copper
Level / move Elevated · +0.9%
What it means Hold price on coils, motors, linesets, wire, service parts
30-year mortgage
Level / move Elevated
What it means Affordability brake on new construction and financed replacement
Watsco WSO
Level / move Q3 Tues 10/27
What it means Dominant weekly public datapoint on A2L margin and demand
Ferguson FERG
Level / move Comp
What it means Broad distribution comp; margin discipline is the valuation anchor
Commodity figures directional for this run; copper, aluminum, mortgage rate confirmed via Markets Insider / Freddie Mac PMMS at time of publish. Equity figures held pending Oct 27 release.
A2L / R-410A exposure exists in inventory or open POs; replacement-cost variance vs standard is material
·
Direct-account or channel-conflict behavior affects contractor accounts
·
Vendor line represents material branch GM dollars, inventory dollars, or AR exposure
·
Northeast footprint overlaps with Watsco / Granite integration
·
OEM public commentary (incl. Watsco Q3) materially shifts pricing or program expectation
Required fields per line: OEM / branch(es) / platform (A2L / R-410A / legacy / mixed) / inventory $ / open PO $ and cancelability / replacement-cost variance / returnability / written supplier protection evidence / Northeast overlap flag / shared account exposure $ / line-level revenue, GM dollars, inventory dollars, supplier dependency ranking / owner / Friday ruling.
09
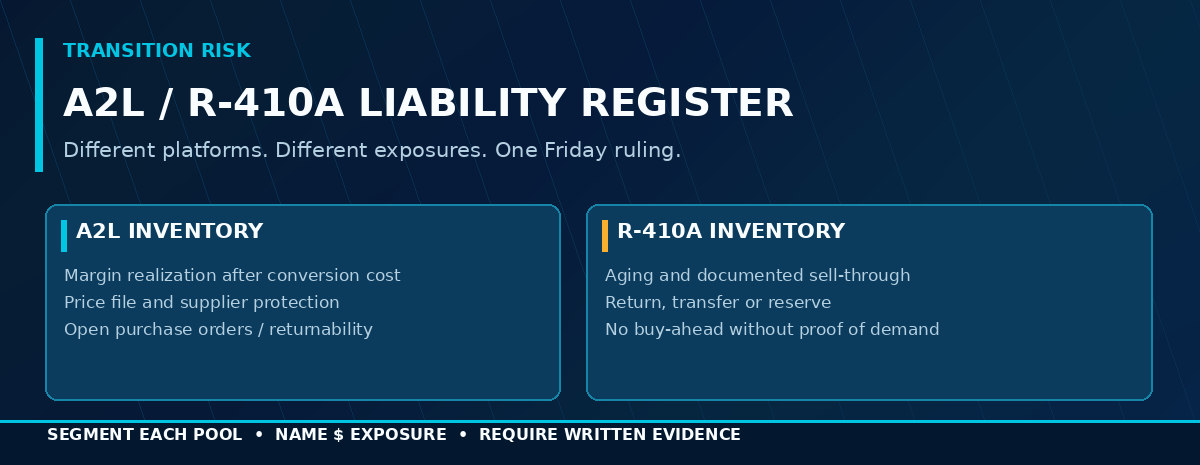
A2L / R-410A Financial Liability Register
Fields: branch / vendor line / SKU / platform (A2L / R-410A / legacy / mixed) / units and $ / cost basis (standard / actual / replacement-cost variance) / A2L conversion cost identified separately per §04 scope / age bucket / 4-week sell-through / open POs and cancelability / returnability / written supplier protection / contractor A2L readiness / disposition (sell → return → transfer with demand → reserve → stop) / owner / Friday ruling.
Finance rule: every pool carries a Finance-approved recovery probability and reserve requirement with named owner, deadline, and financial treatment. Reserve trigger: 90+ days with no documented demand, returnability, or recovery path; or replacement-cost variance exceeding branch-set threshold. R-410A current ample supply does not reduce the forward disposition work.
10
Supplier Scorecard + Leverage Map
Classify each affected line on four axes: supplier objective (inventory clearance, factory utilization, channel discipline, direct-account strategy, platform transition, consolidator response, unknown); likely behavior (push volume with limited protection, hold price discipline, offer selective returns, favor direct accounts, tighten warranty documentation, delay credits); distributor leverage (share of purchases, pull-through, density, A2L technical support, alternatives, line-card dependency, escalation path); negotiation posture (high → demand written protection; medium → trade commitment for returnability; low → limit exposure).
Distinguish confirmed from anticipated: record a supplier program change only when documented in writing. Anticipated supplier reactions to the Granite close are a watch item, not an input to buy-ahead, reserve, or pricing decisions.
11
Account Segmentation + Northeast Playbook
Owner-led residential replacement — fast parts, quote validity, financing sensitivity on larger A2L tickets. Risk: stale quotes, freight leakage, financing fall-through.
PE-backed / consolidated — price leverage, standardized terms, branch coverage; may be targets of consolidator leverage in Northeast. Risk: margin compression disguised as strategic account.
Builder / new construction — release schedules, project pricing, staged deliveries. Risk: AR stretch, delayed starts.
Thinly capitalized owner-led — seasonal cash strain. Response: tight credit limit; COD or partial payment for red accounts.
Northeast overlap playbook · one page per account
1 · Exposure: GM dollars, wallet-share risk, vendor dependence, inventory and AR exposure. 2 · Defense: service, availability, technical support, price architecture, supplier support, cross-sell. 3 · Walk-away point: the margin floor, credit limit, service-cost ceiling, or supplier condition beyond which the business is not worth defending.
Too many distributors defend a customer relationship by quietly funding an unprofitable one. The walk-away point exists to prevent that.
Four questions for every strategic and Northeast-overlap account
1. What share of addressable spend do we have today?
2. Which categories do they buy elsewhere — equipment, controls, refrigerant, IAQ, supplies, parts?
3. Why do they split — price, availability, brand, branch proximity, terms, delivery, technical support, relationship?
4. What would we give up to win that spend, and does the pull-through justify it?
Account-defense approval test
No pricing, credit, delivery, stocking, or service concession is approved merely to preserve revenue. The account owner must show expected incremental annual net contribution after all incremental price, freight, delivery, inventory, return, technical-support, rebate, and credit costs; the result must clear the company’s contribution hurdle and the stated margin floor.
Required fields per overlap or strategic account: current annual sales and GM dollars · estimated addressable spend · current wallet share · incremental wallet-share target · required price concession or program investment · incremental service / delivery cost · incremental inventory commitment · AR / credit exposure · expected annual net contribution · payback period · margin floor and walk-away point.
Each company sets dollar authority bands at each level. Escalation timing: material items ruled by Friday; repeat items escalate one level the following week.
13
Friday Decision Register · with expected economics
Every red exposure receives one of the eight rulings below with named expected contribution and cash impact, weekly and annualized where recurring. “Monitor” is not a ruling.
Ruling
Expected contribution
Cash / working-capital
Repriced
Expected contribution Restores transaction to contribution floor
Cash / working-capital Neutral to positive; may affect volume
Recovered
Expected contribution Captures lost margin or supplier funding
Cash / working-capital Improves AR / cash once collected
Cash / working-capital Requires wallet-share and expiry proof
Each ruling carries a named owner, deadline, and completion status reviewed the following Monday. Northeast competitive-overlap items use the three-part playbook (§11) and name a walk-away point.
30-day proof test · Friday is not a finish line
Each Friday ruling remains open until the stated recovery, disposition, repricing, credit action, or supplier protection is evidenced in transaction data. At 30 days, Finance validates realized contribution, cash effect, reserve adequacy, and any volume or customer-retention consequence. Issues that cannot be resolved by Friday — supplier protection negotiations, aged inventory disposition, wallet-share defense, credit tightening on a strategic account, SKU rationalization — are tracked in the 30-day pipeline, not left in the Friday log.
A durable dollar of avoidable transactional leakage removed generally improves EBITDA by approximately a dollar before tax, provided the recovery does not require offsetting service expense or create compensating volume loss. Cash conversion is separate: Finance should quantify inventory, receivable, payable, rebate, and reserve effects before recognizing free-cash-flow improvement. A recurring improvement that is documented, repeatable, and not dependent on temporary vendor support is materially more valuable than a one-time price recovery.
WHAT BUYERS AND LENDERS SHOULD REWARD
Clean Weekly Net Contribution across A2L and legacy mix · vendor-line files with written supplier protection · platform inventory registers with returnability, cost basis, sell-through, A2L / R-410A split, and reserve logic · branch managers who can explain transfers, freight leakage, counter overrides, and A2L conversion cost in dollars · contractor accounts with documented wallet share and pull-through · Northeast distributors with intact independent contractor loyalty under consolidator pressure.
WHAT BUYERS AND LENDERS SHOULD DISCOUNT
Late-season sales growth without contribution proof · A2L / R-410A comfort narratives without SKU-level and dollar-level exposure · rebate-dependent GM that cannot be tied to documented receivables · project or builder credit expansion without release schedules · cosmetic inventory movement between branches · wallet share dependent on vendor channel assumptions now contestable.
Enterprise-value implication
Strategic and financial buyers generally assign more value to platforms that can demonstrate repeatable gross-margin retention, working-capital control, management depth, and integration capability. Scale without those controls can increase integration and cash-flow risk rather than valuation. Well-run independents remain defendable and acquirable — especially those that can show the stack score cleanly.
How this brief is built
One definition (§04), six KPIs with materiality gates (§06), M/T/W/F cadence (§05), Friday register with named economics (§13). External context in §03 reflects three new primary signals this week; everything else carried. Confidence: High = official release or confirmed scheduled event; Medium = credible trade reporting; Source-limited = held until primary source is in hand. Thresholds are illustrative starting bands — calibrate.
Blue Ops supports HVAC distribution companies across the investment lifecycle. See our HVAC practice →
Primary sources, new this week: Watsco completes The Granite Group acquisition (press release Oct 12, 2026); Watsco Q3 2026 earnings call scheduled Tuesday Oct 27 10:00 a.m. EDT per Watsco IR calendar; Census September 2026 New Residential Construction (released Oct 20 per schedule). Carried: HARDI August TRENDS (reported Oct 13; next release early November); AHRI August 2026 shipment data (released Oct 12; next release mid-November); AHRI R-410A supply commentary (Aug 12 coverage).
Quarantined: OEM-specific 2027 price-file actions pending written release; branch-level allocation shifts attributable to Watsco / Granite close; exact HARDI September and AHRI September figures until primary release; HVAC equipment price range generalizations; state-level seven-day CDD / HDD figures.
Internal data required: every KPI in §06 requires branch-level data. Where the ERP will not link quote, revision, order, invoice, cost, freight, transfer, rebate, return / credit, warranty, and project / customer code, the data gap itself is an enterprise-value issue (§14).
BLUE OPS
Branch-level intelligence for HVAC distribution operators, owners, and buyers.
Prepared for Blue Ops clients and portfolio leadership. Market, commodity, and equity figures are drawn from third-party sources and are provided for discussion only — not investment, legal, or accounting advice. Linked articles remain the property of their publishers.
Blue Ops Partners, 7900 Xerxes Ave South Floor 21 , MN , Bloomington, Minnesota 55431, United States